Injury claims now depend on organized proof, accurate medical records, and a clear explanation of financial harm. Lawyers must connect the accident to the injury, then connect the injury to measurable losses. That process requires more than collecting documents after a client signs an agreement. Attorneys examine timelines, witness accounts, treatment records, and future needs before demanding compensation. The case-building process begins with evidence, then moves toward a damages calculation that supports every dollar requested.
Evidence Starts at the Scene
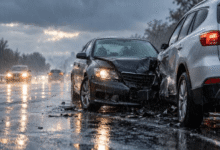
A lawyer first identifies what happened, when it happened, and who controlled the conditions. Police reports, incident reports, photographs, surveillance footage, vehicle data, and witness statements can establish the event’s basic facts. Early preservation matters because video systems overwrite files, vehicles receive repairs, and online posts disappear. A legal team at Poolson | Oden Injury Lawyers often sends preservation requests to businesses, insurers, property owners, or other parties holding relevant records.
Witness accounts require careful comparison. Lawyers check whether each statement matches physical evidence, medical records, and the client’s timeline. Small inconsistencies can create questions, while consistent details can clarify disputed events. People who need guidance after an injury often review their options, especially when medical treatment, insurance communication, and evidence collection happen at the same time. A lawyer can help protect records, identify responsible parties, and organize facts before an insurer shapes the claim around incomplete information.
Medical Records Connect Injury to Cause
Medical evidence must show more than a diagnosis. It should explain when symptoms began, what treatment providers found, and how the condition relates to the accident.
Lawyers compare emergency records with later appointments, imaging results, therapy notes, prescriptions, and specialist opinions. Gaps in treatment receive attention because insurers often argue that delayed care shows a minor injury or an unrelated condition.
A complete medical record also describes functional limits. Difficulty lifting, driving, sleeping, concentrating, or performing household tasks can support damages that a diagnosis alone does not establish.
Damages Require More Than Medical Bills
Economic damages include documented financial losses caused by the injury. These losses can include hospital charges, therapy expenses, prescription costs, transportation, damaged property, and income lost during recovery.
Pay stubs, tax returns, employment records, invoices, and business documents help establish the financial calculation. A lawyer also examines missed promotions, reduced hours, diminished earning capacity, and work restrictions when the injury affects future employment.
Non-economic damages require a different form of proof. Pain, emotional distress, sleep disruption, loss of enjoyment, and changes in family relationships appear through treatment notes, personal journals, testimony, and statements from people who observed the client’s condition.
A damages demand should explain how each loss affects daily life. Specific examples carry more weight than broad descriptions because they show what changed after the accident.
Insurers Test the Case Early
Insurance companies often review liability, medical history, treatment gaps, prior injuries, and recorded statements before making an offer. Their adjusters look for facts that reduce responsibility or lower the claimed value.
Lawyers prepare clients before important communications with insurers. They also review settlement offers against the available evidence, expected medical needs, lost income, and litigation risk.
Comparative fault can affect recovery in many states. Evidence must therefore address the client’s conduct, the other party’s conduct, and the precise cause of the injury. A clear timeline helps separate speculation from supported facts.
Expert Analysis Adds Context
Some claims require testimony from medical specialists, accident reconstruction professionals, vocational consultants, or economists. Each expert answers a defined question tied to liability or damages.
A medical specialist can explain permanent restrictions or future treatment. A vocational consultant can assess whether the client can return to previous work. An economist can calculate future income losses using employment records and medical limitations.
Expert opinions must rely on documented facts and accepted methods. Lawyers review the reasoning behind each opinion because unsupported conclusions face challenges during settlement negotiations or trial.
See also: Law EU Ragnarlockerpagetechcrunch: Understanding the Cybersecurity Landscape
Case Preparation Keeps Evidence Usable
A well-built case includes a dated timeline, indexed records, contact information for witnesses, photographs, expense summaries, and a damages worksheet. Organized files reduce omissions and help counsel respond quickly to insurer questions.
The lawyer also checks whether deadlines affect the claim. Statutes of limitations, notice requirements, medical authorization rules, and court procedures differ by jurisdiction. Missing one deadline can damage an otherwise well-supported case.
Clients improve their records by following treatment plans, saving receipts, tracking symptoms, and reporting work restrictions accurately. They should avoid deleting posts or discussing disputed facts publicly because online material can enter the evidence record.
Conclusion
A successful injury claim connects three facts: another party caused the event, the event caused the injury, and the injury created measurable losses. Lawyers build that connection through timely preservation, consistent medical evidence, financial records, witness accounts, and carefully supported expert opinions. An injured person should begin a dated file immediately, keep every treatment and expense record, and seek legal advice before giving a recorded statement or accepting an insurance payment.